Before anyone thinks about returns, strategies, or markets, one question always comes first: is my money safe with a broker?
This doubt is natural—especially in a world where investing is increasingly digital, platforms are app-based, and there’s no physical branch to walk into. Many people delay investing for years simply because they don’t fully understand how broker safety works.
In this guide, we’ll break everything down clearly and calmly. You’ll learn how brokers protect client money, what real risks exist, what protections are in place, and how to evaluate safety without fear or hype. No promises, no selling—just facts explained in plain English.
Why Broker Safety Is Such a Common Concern
Most beginners don’t worry about market volatility at first. They worry about something more basic:
“What if the platform disappears?”
“What if my money is misused?”
“What if I can’t get it back?”
These concerns usually come from:
- Lack of familiarity with how brokers operate
- Confusing brokers with unregulated platforms or scams
- Comparing brokers to traditional banks without understanding the differences
The good news is that modern brokers are built around safety structures that most users never see, but which exist precisely to protect client funds.
What a Broker Actually Does With Your Money
A common misconception is that brokers “hold” your money in the same way a bank does. In reality, a broker’s role is different.
A broker’s primary function is to:
- Execute trades on your behalf
- Provide access to financial markets
- Safeguard your assets while they are invested
Importantly, reputable brokers are not allowed to freely use client money for their own operations. This is where regulation becomes essential.
The Role of Regulation in Broker Safety
Regulation is the foundation of broker security. A regulated broker must follow strict rules designed to protect investors and maintain market integrity.
These rules typically include:
- Minimum capital requirements
- Regular audits and reporting
- Transparency obligations
- Clear separation between company funds and client funds
Regulation does not make investing risk-free, but it greatly reduces the risk of fraud, misuse, or mismanagement of client assets.
When people talk about “unsafe brokers,” they are almost always referring to unregulated or poorly regulated platforms, not licensed brokers operating under established financial authorities.
Segregation of Client Funds: The Most Important Concept
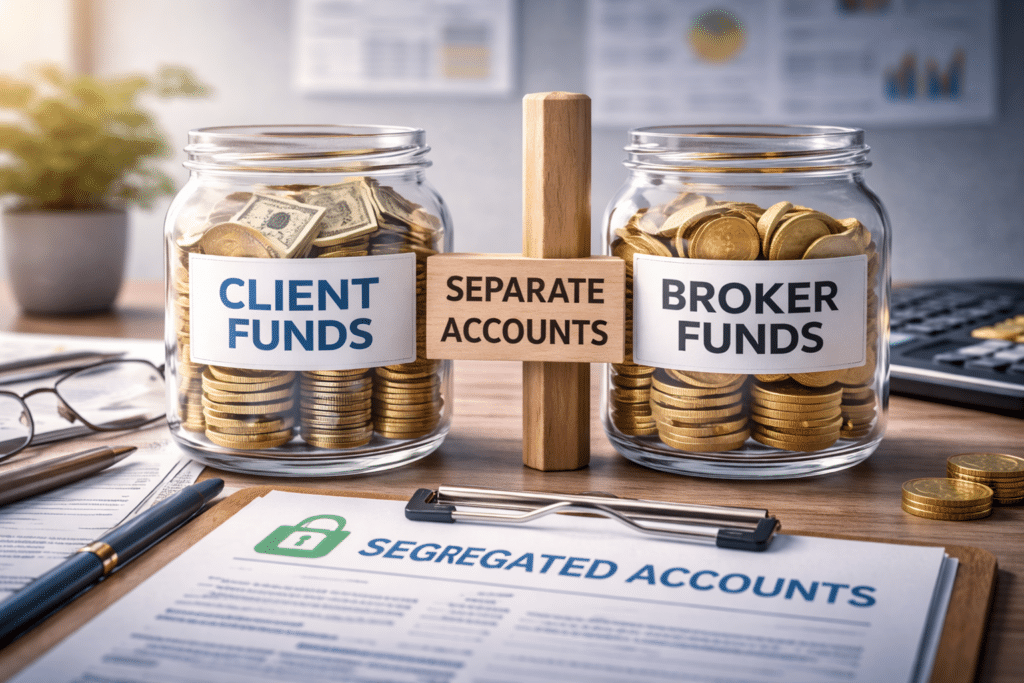
One of the most critical protections in the broker world is segregation of client funds.
This means:
- Client money is kept in separate accounts
- These accounts are distinct from the broker’s operating funds
- The broker cannot use client money to pay expenses or debts
In simple terms, your money is not treated as the broker’s money.
If the company experiences financial trouble, segregated funds are not part of what creditors can claim. This structure exists specifically to protect investors in worst-case scenarios.
What Happens If a Broker Goes Bankrupt?
This is one of the biggest fears—and one of the most misunderstood topics.
If a regulated broker fails:
- Client accounts are frozen temporarily for verification
- An administrator reviews records
- Segregated funds and assets are returned to clients
In many jurisdictions, investor compensation schemes provide an additional layer of protection if something goes wrong during this process.
While delays can occur, total loss of client funds due to broker bankruptcy is rare when proper safeguards are in place. Most high-profile failures that resulted in losses involved platforms that ignored or bypassed regulatory rules.
Broker Safety vs Bank Safety: Are Banks Really Safer?
Banks feel safer because they are familiar and have physical branches. But safety depends on structure, not appearance.
Banks focus on:
- Deposit protection
- Lending and credit
- Daily financial services
Brokers focus on:
- Asset custody
- Trade execution
- Market access
When money is invested—even through a bank—it is usually no longer protected by traditional deposit guarantees. At that point, investment protection mechanisms apply, regardless of whether the investment is accessed via a bank or a broker.
So the question is not “banks vs brokers,” but how your money is protected in each context.
Cybersecurity: Is Online Investing Risky?
Because brokers operate online, many people worry about hacking or data breaches.
Reputable brokers typically use:
- Encrypted connections
- Two-factor authentication
- Secure data storage
- Continuous system monitoring
No online system is perfectly immune, but large-scale security failures at regulated brokers are uncommon. In practice, most individual losses related to security come from weak personal passwords or phishing—not from broker infrastructure failures.
Digital does not automatically mean unsafe; in many cases, it means more controlled and monitored.
Understanding the Difference Between Broker Risk and Market Risk
This distinction is essential.
- Broker risk relates to the platform itself (mismanagement, fraud, failure)
- Market risk relates to price movements of assets
Regulation and segregation greatly reduce broker risk, but market risk cannot be eliminated. Losses caused by market fluctuations are not a safety failure—they are part of investing.
Many people mistakenly blame brokers for market losses, when in reality the platform did exactly what it was designed to do.
Common Myths About Broker Safety
Let’s clear up some persistent misconceptions:
- “Online brokers are less safe than traditional banks”
→ Safety depends on regulation, not format. - “Free brokers are riskier”
→ Pricing models do not determine safety. - “If a broker shuts down, all money is lost”
→ Not true for regulated brokers with segregated funds. - “Apps are inherently dangerous”
→ Technology can increase security when properly implemented.
Fear often comes from misunderstanding, not from actual risk.
How to Evaluate Whether a Broker Is Safe
Instead of relying on brand recognition or marketing claims, look for concrete indicators:
- Clear regulatory information
- Explicit mention of segregated client funds
- Transparent explanations of how money is held
- Accessible documentation about investor protection
A safe broker doesn’t need to promise anything extraordinary. Clarity and transparency are stronger signals than flashy features.
Why Safety Should Come Before Returns
Many beginners make the mistake of focusing on potential gains before understanding protection.
A broker’s job is not to generate returns. Its job is to:
- Provide reliable access to markets
- Execute orders correctly
- Safeguard client assets
Returns depend on decisions, strategy, and time—not on the platform itself. When safety is clear, emotional decision-making decreases and long-term thinking becomes easier.
Final Thoughts: Is Your Money Safe With a Broker?
For most people using regulated brokers, the answer is yes—your money is generally well protected by multiple layers of safeguards. While no financial system is completely risk-free, modern broker structures are designed to minimize the risks that worry beginners the most.
The real danger usually lies in:
- Using unregulated platforms
- Not understanding how protections work
- Confusing market risk with platform risk
Once these distinctions are clear, investing stops feeling like a leap of faith and starts feeling like an informed, structured process.
And that understanding is often the biggest form of security an investor can have.
This article is for informational and educational purposes only and does not constitute financial, investment, legal, or tax advice. Investing involves risk, and readers should make decisions based on their own circumstances or seek professional guidance where appropriate.